What are the VAT implications on the Mainland and Free Zones in the UAE?
VAT implications on the mainland and free zones in the UAE are not the same: mainland businesses and companies in non-designated free zones generally apply 5% VAT on taxable supplies, while only certain free zones specifically listed under the UAE VAT Executive Regulations can be treated as designated zones, where special VAT treatment may apply to some qualifying goods movements. For UK-based entrepreneurs, start-ups, and SMEs setting up or expanding in the UAE, getting this distinction right affects company structure, pricing, imports, VAT registration, and ongoing compliance.
Free zones are economic areas where goods and services can be traded with 100% foreign ownership. Free Zones in the UAE have a different taxation framework from the mainland, which makes them attractive for businesses, but not every free zone gets designated-zone treatment and a designated zone is not a VAT free zone. This guide explains the VAT treatment of mainland versus free zones in the UAE, including designated and non-designated zones, designated zone transactions, VAT registration thresholds, reverse charge issues on movements between zones and mainland, and the records businesses should keep to support VAT returns and avoid errors or penalties.
VAT in the UAE is charged at a rate of 5% on most goods and services. Major peculiarities of free zones are:
-
Attracts 0% tax rates
-
Preferential customs duty rates
-
100% import and export tax exemption
One of the obstacles to free zone companies is the prohibition of direct trade within the local market of the UAE. Offshore companies can appoint a distributor who can offer the goods and services to the local markets, on the agents will get a fee in return.
Designated Zones
Certain free zones listed in the cabinet decision and meeting the conditions set out in the UAE VAT Executive Regulations are called Designated Zones. Not every free zone qualifies: only free zones specifically listed under the UAE VAT Executive Regulations and meeting the required customs-control conditions are treated as designated zones for VAT purposes. For certain qualifying goods transactions, designated zones may be treated as outside the UAE for VAT purposes, but this is not a blanket rule for all supplies. Any supplies between Designated Zones will not attract VAT. Businesses in designated zones must apply for VAT registration if their taxable supplies exceed AED 375,000, which is the standard threshold for mandatory VAT registration over the preceding 12 months. Services provided from designated zones to mainland companies generally follow normal UAE VAT rules, so VAT applicable to services is usually unaffected by designated-zone status unless a specific zero-rating or exemption applies.
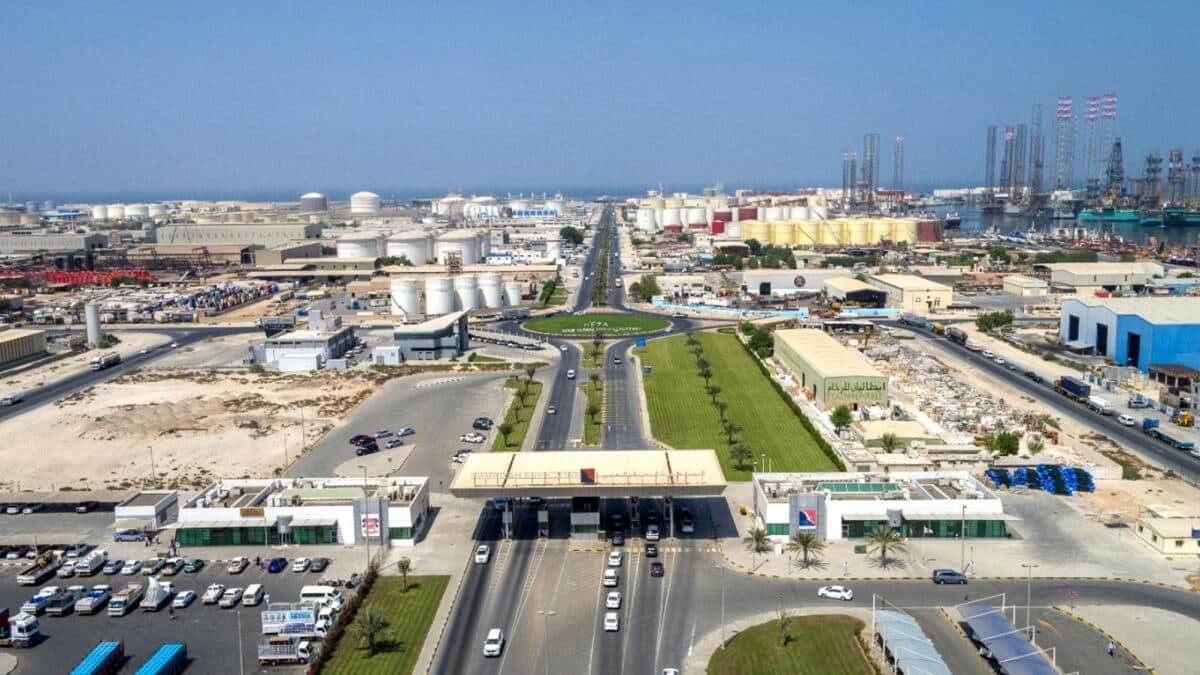
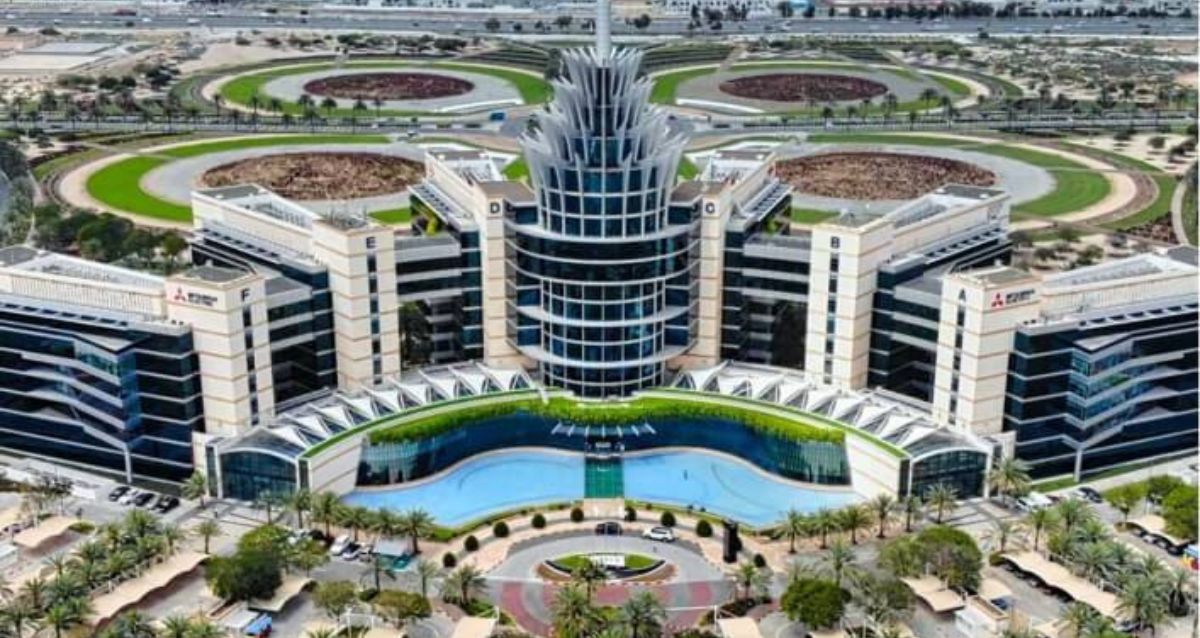
Examples of Designated Free Zones are JAFZA, DAFZA, Dubai Airport Free Zone, RAK Free Trade Zones, etc.
Conditions for Designated Zones;
-
The zone should be within a specific fenced area.
-
The zones should have security measures and customs control over the movement of individuals and goods from and to the zones.
-
The zone should have well-defined internal procedures for the storing, retrieving, and processing of goods within the zone.
-
The operators of the Designated Zones should comply with the rules and regulations set up by the Authority, and businesses must maintain proper records for designated zone transactions, including supporting customs and VAT documents.
-
The movement of goods between designated zones is generally outside the scope of VAT, provided the goods are not consumed or altered during the transfer.
-
Imports of goods into designated zones are not subject to VAT, but VAT applies when these goods leave for the mainland. When goods are imported directly into a designated zone from outside the UAE, no VAT is due at the point of entry. A designated zone is not a VAT free zone: relief mainly applies to certain goods movements, while services within designated zones still follow standard UAE VAT rules, typically at 5%.
Mainland
Mainland in the UAE means the locations outside the Free Zone area. For VAT purposes, Non-Designated Free Zones are treated the same as the mainland, so free zone businesses in those areas generally follow the same 5% VAT rules on taxable supplies and transfers. If a company in a Designated Zone initially bought goods for consumption and paid VAT, and later transfers them to the mainland, import VAT is charged again. A VAT-registered mainland business typically accounts for the import VAT through the Reverse Charge Mechanism in its regular VAT return. The importing company may claim input VAT recovery through its VAT return and recover input VAT when the required documentation is kept and the recovery conditions are met.
A Mainland company is a company which is registered in one of the DED (Department of Economic Development) of the UAE, which will provide a license to start doing business in the UAE.
Types of mainland companies;
-
Joint Liability Company
-
Simple Limited Liability Partnership Company
-
Limited Liability Company (LLC)
-
Public Joint Stock Company
-
Private Joint Stock Company
VAT Implications
|
Zone |
Goods or Services |
From |
To |
Taxability |
|---|---|---|---|---|
|
1. Designated Free Zone |
Goods |
Designated Zone |
Designated Zone |
No VAT |
|
|
|
Designated Zone |
Non-Designated Free Zone |
VAT @ 5% |
|
|
|
Designated Zone |
Mainland |
RCM |
|
|
|
Designated Zone |
Other Countries |
Out of Scope |
|
2. Non-Designated Free Zone |
Goods |
Non-Designated Zone |
Non-Designated Zone |
VAT @ 5% |
|
|
|
Non-Designated Zone |
Designated Free Zone |
VAT @ 5% |
|
|
|
Non-Designated Zone |
Mainland |
RCM |
|
|
|
Non-Designated Zone |
Other Countries |
Zero Rated |
|
3. Mainland |
Goods |
Mainland |
Mainland |
VAT @ 5% |
|
|
|
Mainland |
Designated Free Zone |
VAT @ 5% |
|
|
|
Mainland |
Non-Designated Free Zone |
VAT @ 5% |
|
|
|
Mainland |
Other Countries |
Zero Rated |
|
4. From Other Countries |
Goods |
Other Countries |
Designated Zone |
Out of Scope |
|
|
|
Other Countries |
Non-Designated Zone |
RCM |
|
|
|
Other Countries |
Mainland |
RCM |
Note: designated zone transactions should be reviewed carefully, as the VAT treatment depends on the movement type and the supporting documents kept for each supply. In some cases, free zone entities under common control may form a VAT group, but each member must still take VAT reporting responsibility seriously.
Why choose Flyingcolour Tax Consultant?
According to the requirements of the Commercial Companies Law, all VAT-registered companies must have their financial audits done by a Chartered Accountant who is registered with the Ministry of Finance. Once registered for VAT, companies must file regular tax returns and comply with invoicing and record-keeping requirements. Accurate customs documentation, including import declarations, is essential to justify VAT treatment and for reclaiming input tax, which also helps designated zone businesses defend that treatment and support ongoing compliance. Businesses operating in designated zones must maintain proper records of their transactions for VAT compliance and audits. Strong VAT documentation can also support qualifying free zone status and related access to a 0% corporate tax rate where applicable. A professional tax accountant can ensure that everything is in order, without missing anything, to meet all requirements, so that the organisation does not attract negative attention from the FTA.
Flying Colour Tax Consultant LLC provides audit assistance in resolving tax issues, as auditors can make concrete suggestions for improving the company based on the findings of their records. Additionally, we partner with over 18 agents who are authorised to conduct audits in various jurisdictions, depending on the needs of our clients. Our experts analyse, identify and resolve your business and tax issues. We promise quality and timely support all year round. We provide quality, hassle-free services including Bookkeeping Services, Financial Advisory Services, Consulting Services, Company Registration For VAT in the UAE, VAT return filing, Audit assistance, and a lot more.
FAQ
Q1. Can a free zone sell to the mainland?
Yes, free zone companies can sell goods and services to the mainland UAE; however, such transactions are subject to specific VAT regulations. When a free zone company supplies goods to the mainland, the transaction is treated as an import into the mainland UAE and is subject to the standard 5% VAT. The mainland company receiving the goods is responsible for accounting for the VAT under the reverse charge mechanism (RCM), meaning they declare and pay the VAT in their VAT return, which they can also recover as input VAT if eligible.
It is important to note that not every free zone gets designated-zone treatment, so businesses should first check whether the zone is officially listed before applying those rules. Goods supplied from a designated zone to the mainland are generally outside the scope of VAT for the supplier, with the mainland importer accounting for VAT under RCM. In contrast, supplies from non-designated free zones to the mainland are treated as standard taxable supplies, and the supplier must charge VAT.
For services supplied by free zone companies to mainland clients, normal VAT rules apply, and the supplier must charge VAT at the standard rate of 5%. This also applies where both parties are in the same designated zone, as services generally follow normal UAE VAT rules. Free zone companies should maintain proper records for supplies to the mainland and designated zones to avoid penalties.
Understanding these VAT implications is crucial for free zone companies engaging in trade with the mainland to ensure compliance with the UAE VAT law and to optimise their VAT obligations.
Q2. Is DMCC VAT exempt?
Dubai Multi Commodities Centre (DMCC) is one of the prominent free zones in the UAE and is recognised as a designated zone for VAT purposes. This means that DMCC enjoys a special VAT treatment under the UAE VAT law, but it is not a fully VAT-free zone. Specifically, goods supplied within DMCC or between DMCC and other designated zones are generally outside the scope of VAT, provided the goods are intended for further supply and not for consumption within the zone.
However, it is important to note that DMCC is not entirely VAT exempt. The standard UAE VAT rules still apply to services supplied from DMCC, regardless of its designated-zone status. Services provided within DMCC, as well as goods supplied from DMCC to the UAE mainland, are subject to normal VAT rules. For goods supplied from DMCC to the mainland, the mainland importer must account for VAT under the reverse charge mechanism (RCM). This means that the supplier in DMCC does not charge VAT, but the mainland company receiving the goods must declare and pay VAT in its VAT return, which it can recover as input VAT if eligible.
Additionally, businesses operating in DMCC must comply with VAT registration requirements. If their taxable supplies exceed the mandatory threshold of AED 375,000, they are required to register for VAT with the Federal Tax Authority (FTA) and fulfil all VAT obligations, including filing VAT returns and maintaining proper records. They may also claim vat refunds or recover input VAT on eligible business expenses and zero-rated exports when supported by proper documentation.
In summary, while DMCC benefits from special VAT treatment as a designated zone, it is not fully VAT exempt. Companies operating in DMCC should understand the VAT implications on their transactions, especially those involving the mainland UAE, to ensure compliance with the UAE VAT law and optimize their VAT position.
Q3. Do free zone companies have a TRN?
Yes, free zone companies that meet the mandatory registration threshold are required to obtain a Tax Registration Number (TRN) from the Federal Tax Authority (FTA). The mandatory VAT registration threshold in the UAE is an annual taxable supply exceeding AED 375,000. Free zone companies, including those in designated and non-designated zones, must register for VAT if their taxable supplies and imports exceed this threshold.
Having a TRN enables free zone companies to charge VAT on taxable supplies, file VAT returns, and reclaim input VAT where applicable. This applies to free zone persons and other businesses established in the UAE, including those in designated zones. It is essential for compliance with UAE VAT law and ensures that businesses can properly account for VAT on transactions, including those involving mainland companies and other free zones. Failure to register and obtain a TRN when required can lead to penalties and fines imposed by the FTA. VAT compliance can also matter under uae corporate tax law for businesses seeking qualifying free zone person status.
Therefore, free zone companies should monitor their taxable turnover closely and apply for a TRN promptly once they cross the registration threshold to meet their VAT obligations.
Q4. What is a designated zone in the UAE VAT?
A designated zone in UAE VAT is a specific free zone area recognized under the UAE VAT Executive Regulations, rather than just any free zone, and treated as outside the UAE territory for VAT purposes. This applies mainly to qualifying goods movements, while services supplied there remain subject to standard UAE VAT rules. This means goods supplied between designated zones are generally outside the scope of VAT, and special VAT rules apply to transactions involving these zones.
In some cases, qualifying free zone persons in designated zones may also access tax incentives, including a 0% corporate tax rate, if they meet the conditions.
To learn more about VAT implications on Mainland and Free Zones in the UAE, book a free consultation with one of the Flyingcolour team advisors.
To learn more about VAT implication on Mainland and Free zones in UAE, book a free consultation with one of the Flyingcolour team advisors.
Disclaimer: The information provided in this blog is based on our understanding of current tax laws and regulations. It is intended for general informational purposes only and does not constitute professional tax advice, consultation, or representation. The author and publisher are not responsible for any errors or omissions, or for any actions taken based on the information contained in this blog.